Guides
How much a fence contractor business costs to open, and who lends for it
Fence contractor startup costs, with real dollar ranges and the lenders that fund them, plus the cash gap that decides whether a busy season pays.
What to take away
- A one-crew fence operation opens for roughly $18,000 to $45,000, and most of that is the truck, the trailer and the tools, not the paperwork.
- The gap between paying for materials and collecting the final invoice is what sinks new fence companies, not the total spend.
- Supplier trade credit and equipment finance attack that gap directly; a general bank line is slower and asks for two years of returns.
- Size the deposit against the material order, not the job total, and check your state's cap on advance payments before you set the rule.
What opening actually costs
Registration, a general liability policy and a bond run a few hundred to about $2,000 in most states. That is the cheapest part and the part new owners overthink.
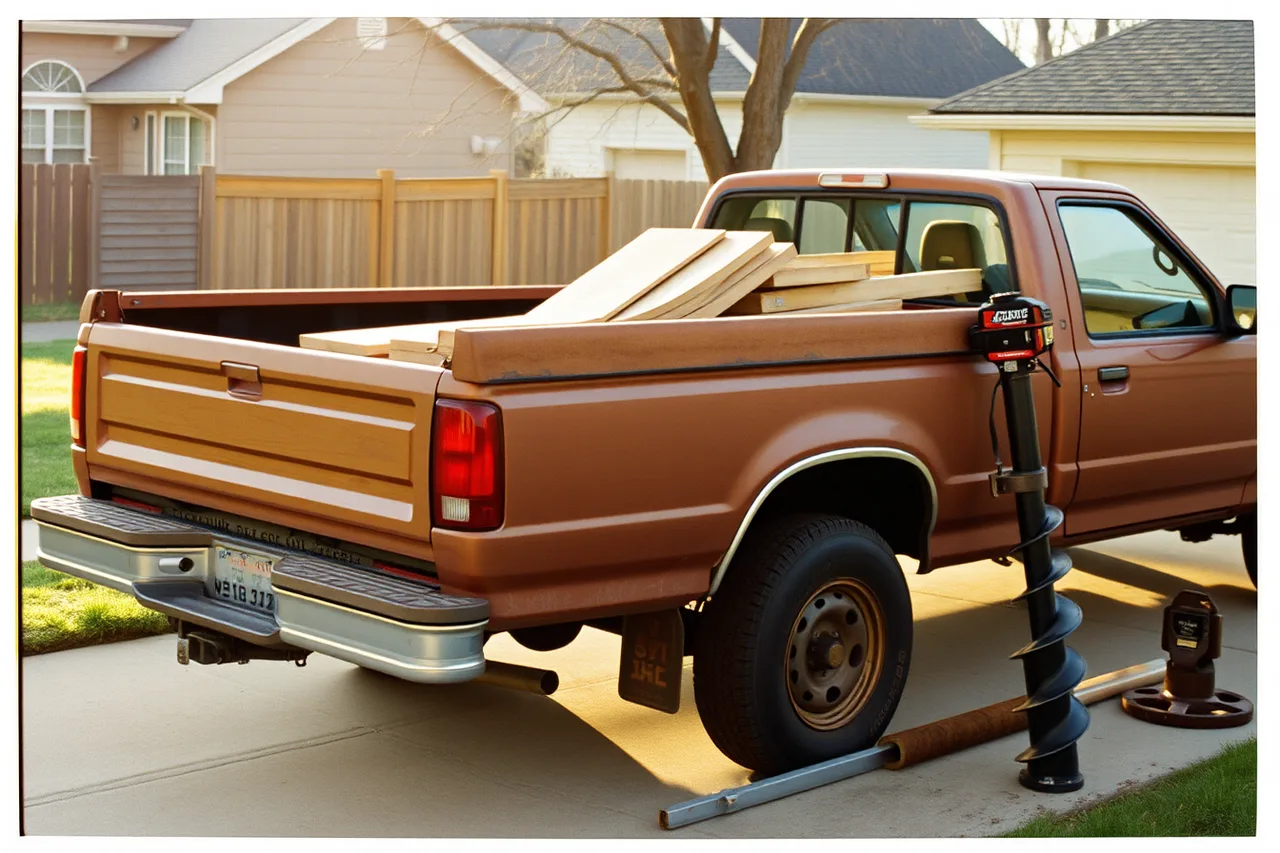
The money sits in iron. A used one-ton pickup with a dump bed or flatbed runs $12,000 to $30,000. A used post driver or hydraulic auger attachment runs $4,000 to $15,000. Hand tools, a mixer, a laser level and safety gear add $3,000 to $8,000. A trailer adds $3,000 to $8,000.
Add a working float for the first job's materials. A 150-foot cedar privacy run carries $2,500 to $5,000 in posts, panels, concrete and gate hardware at order. That is cash out before anyone digs.
| Item | Typical range | When it leaves |
|---|---|---|
| Registration, insurance, bond | $500 to $2,000 | Before first job |
| Used truck, dump or flatbed | $12,000 to $30,000 | Before first job |
| Post driver or auger attachment | $4,000 to $15,000 | Before first job |
| Hand tools, mixer, trailer | $3,000 to $8,000 | Before first job |
| First job materials | $2,500 to $5,000 | At material order |
Those ranges are illustrative and move with your market. A new truck instead of used can double the largest line. Renting the machine instead of buying it removes $4,000 to $15,000 from day one and adds a daily rate to every job that needs it.
Why the total is not the number that matters
Two operations can each spend $30,000 to open and be in completely different shape. What separates them is when money leaves against when it comes back.
Set the model up in named quantities and fill them from your own records.
- Fixed setup.Registration, insurance, the vehicle, the tools you own rather than hire. Paid once.
- Job materials.Posts, panels or fabric, concrete, hardware and gate components for one job, paid at order.
- Job labor.Crew hours times the fully burdened hourly cost, paid on your payroll cycle whether or not the customer has paid.
- Deposit rate.The share of the job price you collect before ordering.
- Order lead time.Days from placing the material order to being able to start.
- Cure delay.Days between setting posts and hanging panels and gates.
- Payment lag.Days from final invoice to cleared funds.
- Jobs in flight.How many of these cycles overlap.
The two derivations that decide everything
Does a deposit fund its own job? Compare the deposit against materials plus the labor you pay before the final invoice clears. If the deposit is smaller, every job you sell ties up more of your own cash.
Selling faster makes it worse. This is the arithmetic behind the fence company that is busy and broke in the same month.
How long does a job hold your cash? Add order lead time, install days, cure delay and payment lag. Multiply that span by jobs in flight and you have the working capital the operation demands at a given pace. Growth raises jobs in flight, which is why a strong season can create a cash problem rather than solve one.
A worked illustration in symbols
Take one job. Call the price P, the deposit rate d, materials M, and pre-payment labor L.
Before final payment, cash out is M + L and cash in is d times P. The job funds itself when d times P is at least M + L. It drains the business when it is not.
Hold that shortfall as S and multiply by jobs in flight N. That product is the cash you must already have to run at that pace. Nothing here needs a currency figure to be useful. It needs your own M, L, d and N, which come from your records.
What moves each quantity in fence work
Materials follow the fence type and the ground. Deeper holes mean more concrete. Slope means stepped panels and more posts across the same run. A gate is a small share of the length and most of the hardware.
Lead time is the quantity new owners underestimate. Stock panels in one color and one height may be same week. Anything a homeowners association has to approve may not be. Cure delay is set by the product and the weather, not by your schedule.
Payment lag depends on the buyer. A homeowner usually pays at completion. A builder pays on someone else's terms, and those terms are a funding decision wearing a sales decision's clothes.
Who actually lends for this
Four sources fit a fence operation, and each behaves differently against the model above.
Supplier trade credit. Your lumber yard or fence distributor extends 30-day terms on materials once you have a history. This attacks the largest line in the gap directly. Ask for net 30 at account setup, before you need it.
Equipment finance. A dealer or a lender like Sheffield Financial writes a note against a specific machine, often with little down. It turns a fixed setup cost into a monthly payment, which helps cash and raises the cost of every job the machine touches.
SBA 7(a) and microloans. The 7(a) program backs bank loans up to $5 million through participating lenders; SBA Microloans run to $50,000 through nonprofit intermediaries. Both want a business plan and, usually, some trading history. The SBA business guide lists the routes and what each expects.
Business credit cards and a bank line of credit. Fast and expensive, or slow and cheap. A card covers a material order this week. A line of credit takes two years of returns and a personal guarantee.
The IRS starting a business pages cover the entity and recordkeeping choices that decide how these amounts get accounted for.
If any work happens above grade, budget for the controls in the OSHA residential fall protection guidance rather than treating them as an afterthought.
The fence contractor business plan ties the model together. Broader context sits in the fence contractor startup and market guide.
What you buy up front is a separate decision: the fence contractor equipment and setup guide and the equipment checklist for new owners. The first months' sequencing sits with starting a fence contractor business.
Building your own version
- List every amount paid before your first invoice clears, marked fixed setup or job specific.
- Take a real recent quote and fill in materials, pre-payment labor and the deposit you intend to collect.
- Compute the shortfall on that job without assuming the customer pays early.
- Decide how many jobs you will have in flight in your busiest month.
- Multiply, and compare against the cash you actually have.
- If the gap is uncomfortable, change the deposit rule or the pace before changing the funding plan.
Common questions
What deposit should I take?
Enough to cover the material order and any labor paid before the final invoice clears, subject to what your state allows. Some states cap advance payments on home improvement contracts. Ask the state consumer protection office or your contractor licensing board before setting a policy.
Can I start without owning a machine?
Yes, and many operators should. Hire the driver or auger for the jobs that need it and record what it saves. If the machine sits idle most weeks, owning it converts a variable cost into a fixed one at the wrong stage.
Why does a busy season create a cash problem?
Jobs in flight rise, and each one holds cash from material order until final payment clears. More work means more of your own money committed at once. The fix is the deposit rule and the payment terms, not more selling.
Should I quote in linear feet?
Present it that way if the customer expects it, but do not cost it that way. Gates, corners, slope, rock and access are not proportional to length, and a length-only rule quietly rewards the customer with the worst site.